 Jovis AI
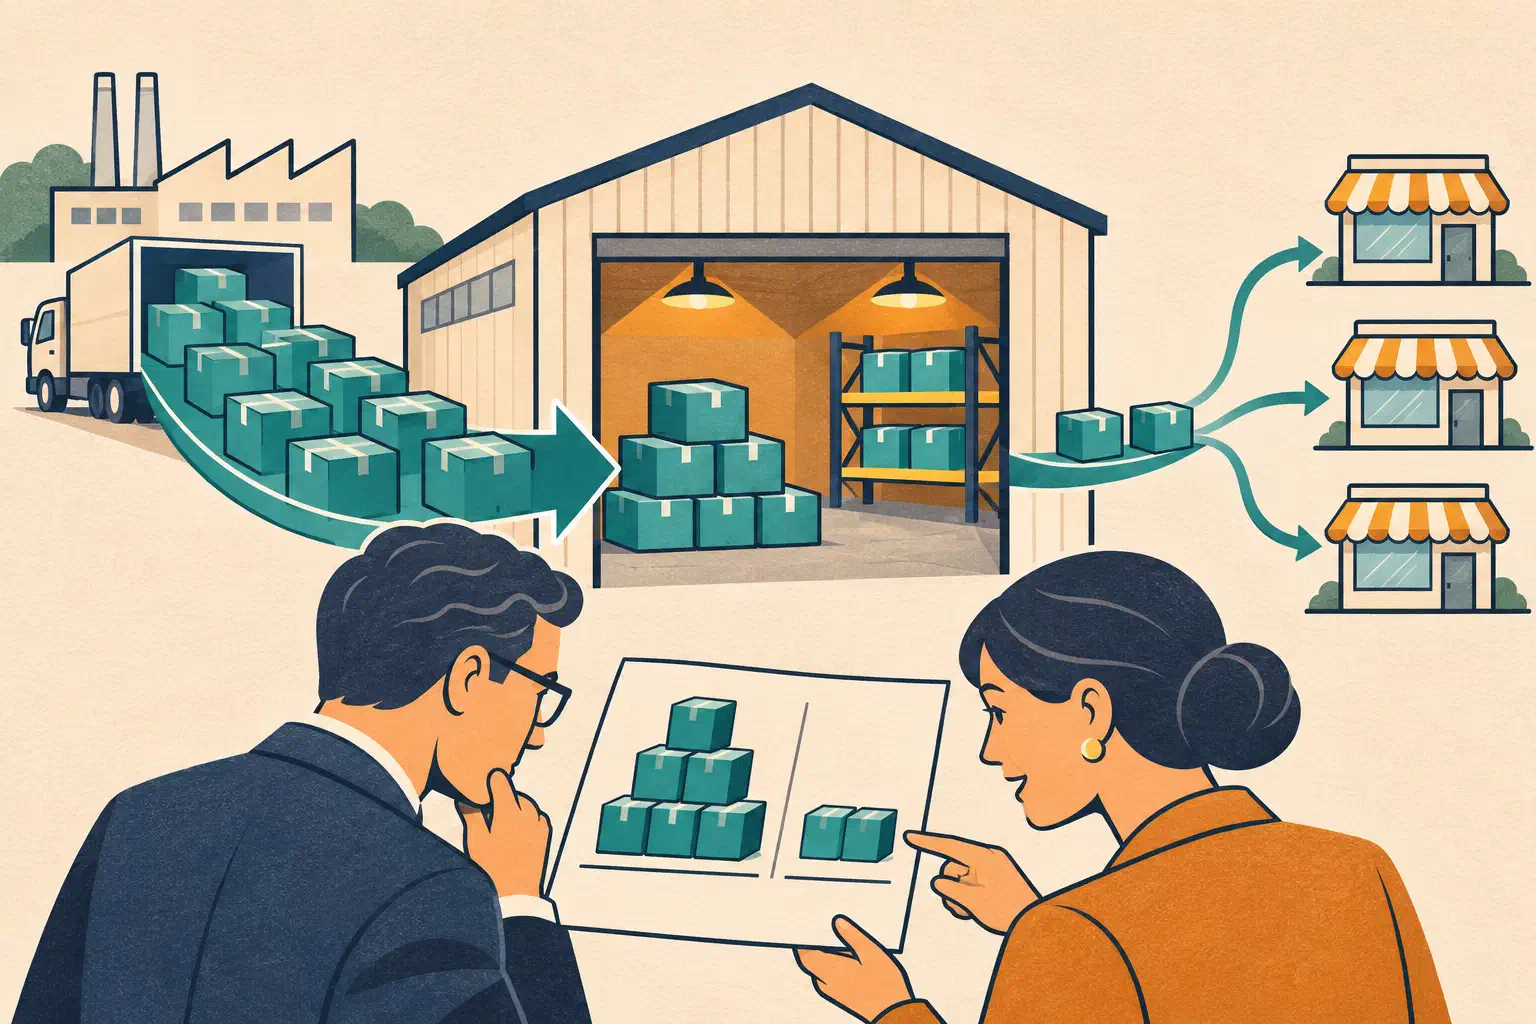
A reseller exceeds its quarterly purchase target and asks for more marketing funds. The CRO sees growth. The CFO sees rising rebates. Operations sees stock accumulating downstream. Before rewarding the result, leadership needs to establish whether the partner is building end-customer demand, preparing for a documented launch, or simply buying ahead.
AI channel partner performance analysis uses AI to assemble and explain evidence about a partner’s commercial results, downstream demand, and support requirements. A useful executive review keeps those measures separate, reconciles their differences, and connects them to a specific funding or support decision.
This guide focuses on distributors and resellers that hold physical inventory. Referral partners, service firms, and software marketplaces need different measures; warehouse stock is not a useful proxy for their contribution. The workflow below is general implementation guidance, not a claim that Jovis has specific channel-management integrations or a ready-made partner scorecard.
Decide what the partner review can change
Start with a choice that the CRO and CFO actually own: expand discretionary marketing support, fund a targeted enablement effort, maintain the current plan, or investigate before committing additional resources.
Separate discretionary support from contractual entitlements. An executive review can recommend a new investment; it should not quietly suspend an earned rebate or rewrite an existing agreement. Have the appropriate commercial, finance, and legal owners review any proposed change to obligations.
A practical review question is:
For established resellers in one region, where does the evidence justify additional discretionary support next quarter? Compare end-customer demand, stock position, channel costs, and the partner’s agreed plan. Identify what we must verify before approving an increase.
Keep comparisons within meaningful peer groups. A new distributor stocking its first territory and a mature reseller replenishing an installed base have different jobs. Record partner tenure, product mix, territory, and launch commitments before interpreting a difference as underperformance.
The scope also determines what this meeting should leave to other reviews. Pipeline-risk investigation examines open opportunities and forecast assumptions. This review examines whether a reseller’s results support further channel investment, including what happens after the reseller places an order.
Keep shipments, demand, and economics visible
A single partner score can hide the disagreement that executives most need to understand. Use three views before attempting any overall rating.
Commercial activity: what entered the channel?
Track orders, shipments, credits, and the relevant commercial targets under explicit definitions. An order accepted, a carton shipped, and revenue recognized are different events. The controller owns the reporting basis; a management review should not infer accounting treatment from physical movement.
Standard partner reporting provides useful starting measures. Salesforce’s PRM reporting documentation lists open opportunities by partner, quarterly closed revenue, partner fund requests, and fund claims. Those records help describe activity and support, but leadership still needs to specify which decision they inform.
Downstream demand: what left the channel?
For this review, define sell-in as units received by the reseller from the supplier, and sell-through as units sold onward to end customers. In a multi-tier network, sales from a distributor to another reseller are an intermediate movement. Identify which reporting tier you can actually observe before calling a measure end-customer demand.
Oracle’s consumption-driven planning documentation maintains distinct sell-through history, inventory, and replenishment measures. That separation is useful here: a shipment into a reseller does not establish that the same quantity has reached customers.
Ask for stock on hand, customer sales, returns, and any transfers needed to reconcile the movement. If downstream reporting is unavailable, label demand visibility as incomplete. Purchase frequency can support a question about demand; it cannot fill in a missing sales report.
Economics: what support did the result consume?
Bring together the approved revenue basis, product costs, rebates, credits, marketing support, and attributable service costs. Finance should specify where each item is already recorded so a rebate netted against revenue is not subtracted again.
Oracle’s channel rebates and point-of-sale management data sheet describes separate views of trade-spending commitments, earnings, and payments. Apply that distinction to the review: cash paid this quarter is not automatically the full cost of the quarter’s support.
Use the resulting management contribution measure to explain current economics. For a proposed funding change, compare the future costs and benefits separately. The customer-profitability decision guide explains why attributed costs and costs that actually change require different treatment.
A worked example: purchase growth with flat customer sales
The following is an illustrative example, not a Jovis customer result. Assume one mature reseller, one product family, and two comparable 13-week quarters. All units use the same product definition. There are no returns, stock transfers, losses, or in-transit differences.
| Reconciled measure | Previous quarter | Current quarter |
|---|---|---|
| Opening reseller inventory | 1,000 units | 2,000 units |
| Units received from supplier | 8,000 | 10,000 |
| Units sold to end customers | 7,000 | 7,000 |
| Closing reseller inventory | 2,000 | 5,000 |
Both periods reconcile: opening stock plus receipts minus customer sales equals closing stock.
Receipts grew 25%, while end-customer unit sales were flat. Closing stock increased by 3,000 units during the current quarter. At the current quarter’s average sales pace of approximately 538 units per week, the 5,000-unit closing balance represents about 9.3 weeks of stock.
That is a backward-looking coverage estimate, not a demand forecast or a universal inventory threshold. A seasonal launch, longer replenishment lead time, or agreed service-stock requirement could justify it. Compare the stock with the partner’s documented plan and product-level availability before drawing a conclusion. Aggregate inventory can also conceal a shortage of one model alongside excess stock of another; the inventory forecasting guide addresses the replenishment decision in more detail.
Suppose the reseller requests another $40,000 of discretionary marketing funds. Leadership has at least three choices:
- Expand support: appropriate only if the proposed activity has a credible objective, delivery plan, and economic case. Purchase growth alone does not supply that case.
- Run a limited demand-generation test: fund a smaller, defined activity with an agreed audience, spending cap, and measurement plan before expanding it.
- Hold additional discretionary funding while verifying the stock build: appropriate when the inventory reconciliation or demand explanation remains unresolved, subject to existing commitments.
Flat sales do not prove that prior support failed. Sales might have fallen without it, or the activity may target a later period. Equally, a subsequent sales increase would not by itself establish that the additional funds caused it. Label the strength of the evidence and choose a test where causal uncertainty affects the investment decision.
Reconcile the records before asking AI for an explanation
Give channel operations responsibility for a compact evidence set, with finance validating the economic definitions. The records may come from approved exports or governed connections. Verify availability, permitted use, freshness, and access for each source before designing the workflow around it.
At minimum, resolve these questions:
- Identity: Which legal entities, branches, and reporting accounts belong to this partner? Use reviewed identifiers; similar company names are insufficient.
- Product: Do supplier SKUs match the reseller’s product codes and units of measure? Resolve bundles and pack sizes explicitly.
- Timing: Are supplier shipments being compared with reseller receipts? Preserve both dates and account for goods in transit at the cutoff.
- Movement: Can opening inventory, receipts, sales, returns, and transfers explain closing stock? Show unresolved differences rather than forcing a balance.
- Coverage: Which locations and products reported, through what date, and with what corrections? A missing location is not zero sales.
- Economics: Which support amounts are committed, earned, accrued, or paid, and where are they included in the contribution calculation?
Attach the partner plan and the relevant commercial terms to those reconciled measures. Together, they let a reviewer distinguish an unexplained stock build from one the business intentionally funded.
Set the failure rule in advance. Missing downstream data may permit a limited commercial review while blocking any conclusion about end-customer demand. Conflicting inventory should trigger reconciliation. The data-quality guide for AI agents provides a method for deciding when to block, limit, or qualify an output.
Give AI the comparison work and executives the investment choice
Once the measures are reproducible, test AI on locating relevant approved plan notes, identifying contradictions, and drafting questions for the partner owner. Keep arithmetic and metric definitions in approved calculations. Require links to the records behind each substantive explanation.
An illustrative request could be:
Prepare a funding-review brief for this reseller using the supplied reconciled measures and approved plan records. Explain differences between receipts, downstream sales, and stock. Identify documented reasons, competing explanations, and missing evidence. Compare maintaining support, a limited test, and expanded support. Do not infer missing customer sales, determine rebate entitlement, contact the partner, or change any record.
For the worked example, a useful output would state that inventory accumulated while reported customer sales remained flat, then check for an approved stocking plan. It should distinguish a documented launch from a partner manager’s unverified expectation. The proposed next step might be to confirm launch timing and SKU availability before reviewing the funding request.
Treat partner submissions and meeting notes as evidence. A statement asking for preferred status is a request to evaluate, not authority to change the program. Keep internal economics and other partners’ information out of any partner-facing brief unless separately authorized.
Leave the review with a short investment record
Use one decision page, with supporting evidence available behind it:
- Decision: amount, purpose, period, and accountable approver for the discretionary support under review.
- Performance: reconciled commercial results, downstream demand, stock position, and finance-approved contribution view.
- Explanation: documented causes, alternative interpretations, and unresolved evidence.
- Options: maintain, test, or expand support, including what each requires and how it affects existing commitments.
- Follow-through: partner owner, verification tasks, review date, and the outcome that would change the decision.
Before relying on the process, replay a completed quarter containing late reporting, a return, a product-code change, and a legitimate planned stock build. Check that the workflow preserves each distinction. Track unsupported explanations, reconciliation failures, reviewer corrections, and decisions reopened because evidence was missing.
Carry approved commitments forward with an owner, source, and review date. A promise to fund a launch should be available at the next review; an old preference to prioritize a partner should remain challengeable. This is a useful application of the AI Chief of Staff vision: continuity across commercial evidence and relationship history, with a simple decision page for the leader. It is a design goal, not evidence of a current Jovis memory or automation feature.
Jovis describes its role as finding relevant company context and preparing leaders for decisions. A reseller investment review is a concrete problem against which to assess that approach, after confirming the required sources and controls. The executive standard is whether the review explains the gap between channel purchases and customer demand well enough to make the next funding choice defensible.