 Jovis AI
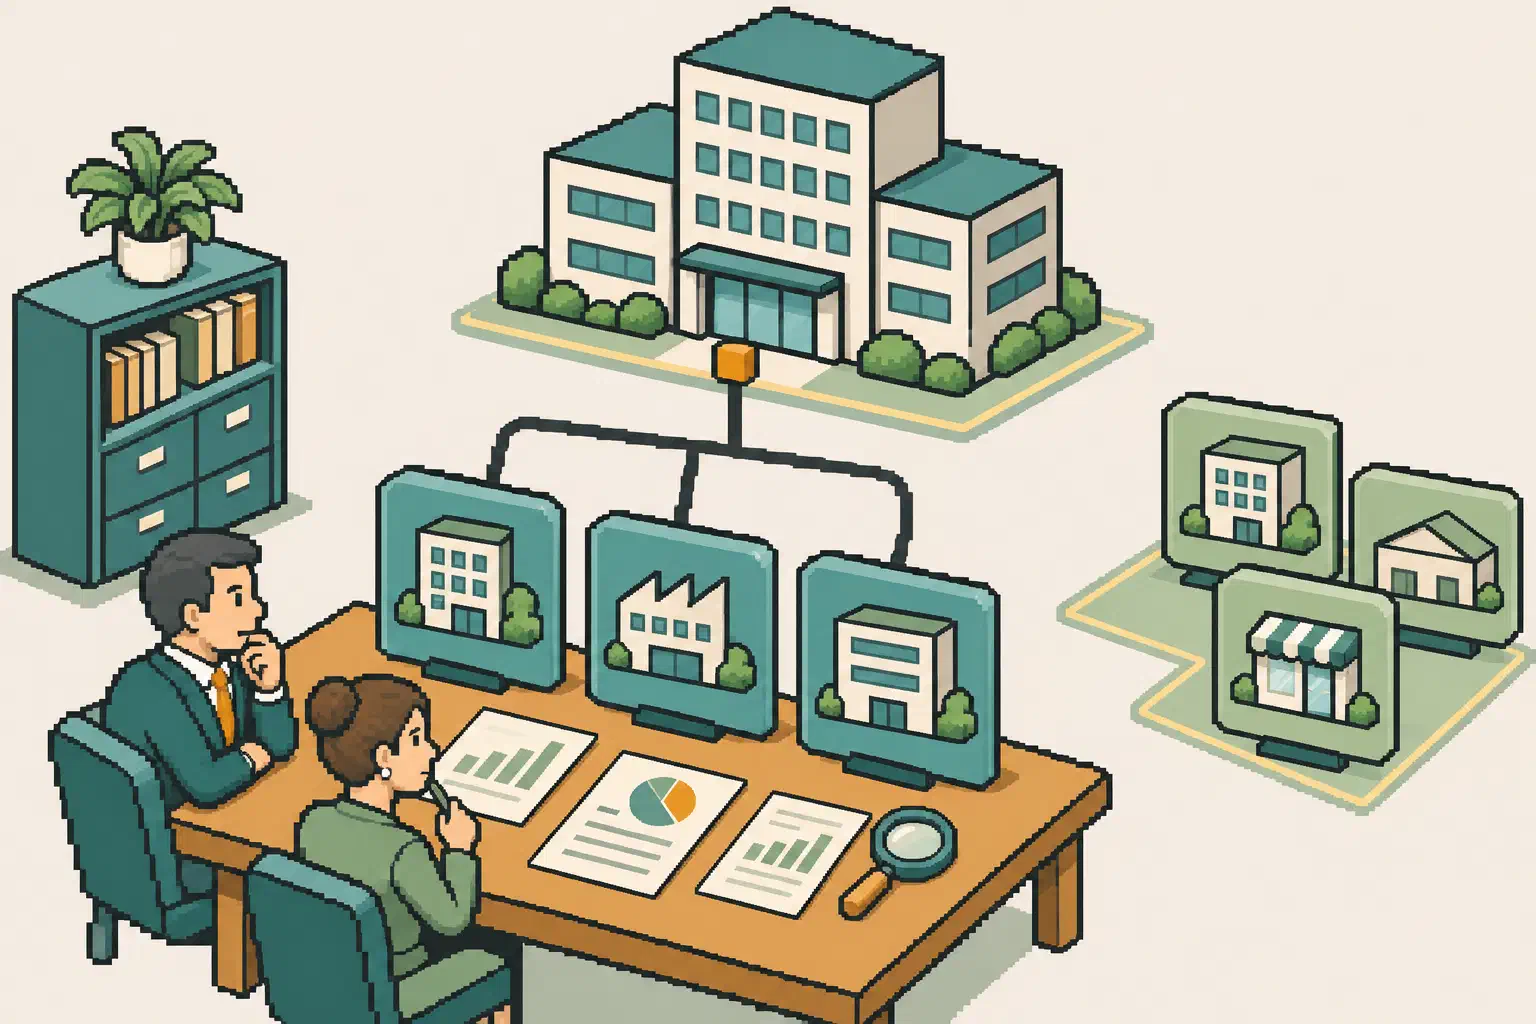
Customer concentration risk is dependence on a small number of customers for a material share of revenue. For a CFO and CRO, the first question is whether apparently separate accounts share one buying decision. Three subsidiaries can look diversified in a sales report while exposing the business to one budget cut.
Before approving dedicated capacity or another expansion discount, establish the combined exposure and who controls the next purchase.
Group the dependency before calculating the percentage
Start with revenue for the latest closed twelve months, reconciled to finance’s approved total. Use the same currency and treatment of credits throughout.
Map each billing account to its verified parent. Salesforce’s account-hierarchy guidance illustrates how separate location accounts can be linked through a Parent Account field. That structure is a starting point; it does not prove centralized purchasing.
Ask the commercial owner to confirm:
- Which entities share procurement, a renewal negotiation, or a budget owner?
- Which contracts can change independently?
- Which links remain unverified?
Keep legal ownership and buying dependence as separate fields. Two subsidiaries may buy independently; unrelated distributors may depend on the same end customer. Preserve unknowns instead of assigning a parent from a similar name.
Example: three 6% accounts become an 18% exposure
Consider a hypothetical business with $20 million in annual revenue. Three accounts each contribute $1.2 million, or 6%. Verified ownership records put them under one parent, and their commercial owners confirm a shared renewal negotiation.
The combined exposure is $3.6 million ÷ $20 million = 18%.
If purchases across that group fell by half for a full year, with unchanged prices and no replacement sales, annual revenue would fall by $1.8 million. This is a scenario, not a forecast of customer behavior or the effect on profit or cash.
The executive choice might be to stage dedicated hiring until the renewal is resolved, rather than commit all capacity immediately. A strong relationship can still justify investment; the point is to make the dependence explicit.
Give AI a bounded evidence job
A proposed AI-assisted review can compare approved billing records, account relationships, signed agreements, and commercial-owner notes. Use ordinary calculations for totals; use AI to locate supporting passages, highlight contradictions, and draft questions.
An illustrative request:
Show our largest customer groups using finance-approved revenue and verified account links. Separate common ownership from shared purchasing. Cite the evidence, show unresolved mappings, and identify renewals requiring executive review.
Require one short output per group: revenue share, purchasing authority, relevant contract dates, evidence gaps, and the decision requested. Verify extracted dates against governing agreements using the contract-obligation review process. This is implementation guidance; Jovis connector support and this specific workflow remain unconfirmed.
Turn exposure into an owned growth decision
BDC’s diversification guidance identifies dependence on one client or sector as a vulnerability. Broader growth needs a deliberate owner and budget.
Have the CFO approve the exposure calculation, the CRO validate purchasing dependence, and the COO review capacity commitments. Record the chosen response and a review trigger, such as a renewal decision or parent acquisition. Feed the result into the executive risk review.
Before introducing AI into preparation, use the AI evaluation checklist on one completed review, including a false parent match and a missing contract.